
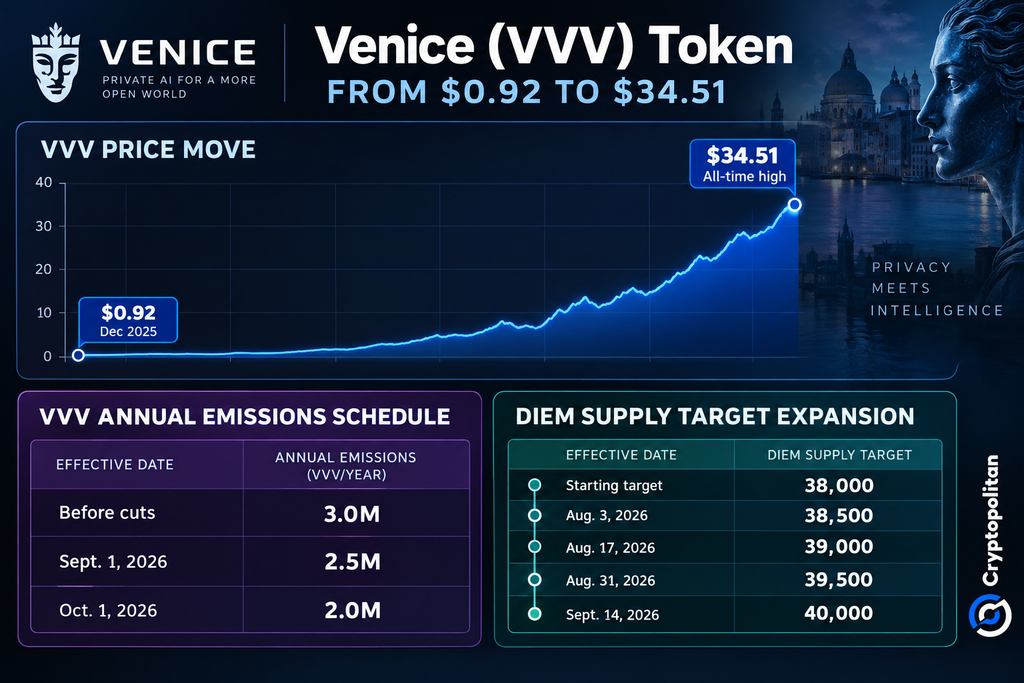
Venice (VVV), the cryptocurrency associated with the privacy-oriented AI platform Venice started by Erik Voorhees, founder of ShapeShift, peaked at a record $34.51 on September 21 but then came down to around $31.
Thus, as of now, VVV is approximately 3,000% higher than the low of $0.92 reached in December 2025 (note that this is a low and high price comparison, not a comparison of total annual performance) and has a market capitalization of approximately $1.5 billion.
Decrypt said VVV is the third-largest cryptocurrency by AI application, behind Near and Bittensor’s TAO. However, rankings may vary per methodology with Internet Computer ranked ahead of VVV, according to CoinGecko. The question remains if the demand for private AI would sustain the token after the initial excitement is over.
Why VVV is an access key, not a stake in the company
VVV does not provide a claim on the ownership of Venice AI. It is an ERC-20 token on Base with utility related to compute access. Users can stake VVV to earn yield and gain access to Venice Pro, according to Venice’s description.
By staking 100 VVV, users can claim Pro access with unlimited text prompts and use of models related to images and videos.
The DIEM twist that behaves like a subscription
VVV stakers can also lock their staked tokens in order to mint DIEM. According to Venice, one staked DIEM serves as the equivalent of $1 daily API credits that are refreshed daily.
In July, Venice increased the target DIEM supply from 38,000 to 40,000 in four steps: 38,500 on August 3, 39,000 on August 17, 39,500 on August 31, and finally 40,000 on September 14.
Cutting emissions while burning the float
The same tokenomics update lowered the yearly expected VVV emissions from 3 million tokens to 2 million tokens in two installments: 2.5 million from September 1 and 2 million from October 1. Venice also launched an API-credit burn, allocating $5 of each $100 spent on credits to the acquisition of VVV tokens in the secondary market and their subsequent burning, in addition to the already existing burns funded by subscription revenues.
$65 million in equity, and why that is not the token
Venice raised a $65 million Series A led by Dragonfly at a $1 billion equity valuation in July. The Block reported that investors received an 8.98% equity stake, a vesting grant of 1.5 million VVV and warrants to buy another 5 million VVV over eight years.
Voorhees framed Venice’s token position more directly:
“Venice, the company, remains the largest holder of VVV, owning more than 30 million out of today’s 80 million supply. The company has not sold any to date.”
The wording comes from Voorhees’ funding announcement, whose claims were also reported by The Block. He also told the outlet, “We don’t want to sell the token.” Venice reported more than $70 million in annualized run-rate revenue and said it had become profitable.
Where VVV fits in the AI and privacy-coin trades
Coinbase’s Institutional team categorizes VVV with both TAO and VIRTUAL as distinct ways of deriving value from AI crypto and characterizes VVV as “tokenized inference”. Galaxy also makes a comparable argument by using Venice as an illustration of how to transform future inference access into a property that can be owned and transferred and mentions that, in 2026, inference has overtaken training in terms of global GPU demand.
VVV has also benefited from a broader privacy trade. Citing Glassnode, 24/7 Wall St. said privacy coins led ten crypto sectors over the previous 30 days with a 90% collective gain, although Zcash accounted for much of the move. Cryptopolitan previously covered VVV’s 100% weekly jump in March after Venice became the recommended provider for OpenClaw.
The case for caution
A research preprint titled “AI-Based Crypto Tokens: The Illusion of Decentralized AI?” argues that many AI-token projects still rely heavily on off-chain computation and can resemble centralized AI services with token layers added on top. Venice itself gives users access to more than 200 models, including closed-source systems from OpenAI and Anthropic routed anonymously through its API, according to The Block.
That leaves several risks: a concentrated treasury position, future warrant-related supply, dependence on third-party models and the capital demands of building proprietary compute infrastructure. The burn-and-staking thesis ultimately depends on sustained product usage, not simply a rising token price.
The smartest crypto minds already read our newsletter. Want in? Join them.